Structure A
Lower retention
The carrier holds more of the risk. Higher premium, most predictable cost.
PremiumHigh
Retained riskLow
Cash-flow variabilityLow
Your HUB team · HUB International · Program review
Built for Obie Companies
Prepared for the leadership of Obie Companies ahead of the broker decision. What we read, what we found, and how we would run the next placement.
Prepared October 2026 · Eugene, Oregon
What we found
We have already read the full program, so we know where it stands today. From here, the work is making it one program on one renewal date, so insurance becomes something Obie handles once a year rather than manages all year. The headlines from our review are below.
Lead producers
Review
Seven policies and four endorsements, read against each other, not one at a time.
Tower
Excess layers renew in January over a primary program that renews in March.
Hospitality
One limit, defense included, with exclusions at both layers above it.
Residential
Outside the excess tower, at roughly a quarter of the portfolio's liability limits.
Property
One $5M limit across four hotels at a 10% deductible.
Start
Every entity, every location, and the policy that answers for it.
Appoint HUB as broker of record and we start the program review the same week.
The work behind it
The same disciplined path on every account, applied to Obie from the day the broker of record letter is signed.
Every policy, endorsement and lender requirement read against the entity and location schedule.
Entities, locations, values and operations reconciled into a single source the market can underwrite.
Obie's hotels and properties presented to carriers before the first submission goes out.
Lines, layers and renewal dates agreed with ownership before any carrier is approached.
Options compared and narrowed to one recommendation, with the trade-offs in writing.
Provisional broker review
Provisional review. October 14, 2026.
The supplied program represents substantial property and liability insurance, with multiple carriers, several operating entities, a hospitality exposure, and significant insured real estate values.
The first priority is reconciling the excess liability tower. Chubb's January 1 excess policy identifies a $5 million Union Insurance Company umbrella as controlling underlying insurance. A separate Fireman's Fund umbrella begins March 1. These policies cannot automatically be treated as one uninterrupted, coordinated liability tower.
This is a material clarification, not a confirmed coverage lapse. Written confirmation of the underlying-policy change and Chubb's acceptance is necessary before representing the full limits as available.
The principal limits extracted from the issued documents are:
| Coverage | Carrier | Principal limits |
|---|---|---|
| Property | Fireman's Fund | $189.33M building blanket; additional scheduled property limits |
| Business income / extra expense | Fireman's Fund | $34.29M blanket plus scheduled limits |
| Earth movement | Fireman's Fund | $5M event/aggregate at specified locations |
| Equipment breakdown | Fireman's Fund | Applicable property/BI limits; extensions have sublimits |
| Mobile equipment | Fireman's Fund | $50K unscheduled; $200K leased/rented |
| Data compromise | Fireman's Fund | $50K aggregate |
| General liability | Fireman's Fund | $1M occurrence / $2M aggregate |
| Liquor liability | Fireman's Fund | $1M common cause / $2M aggregate |
| Employee benefits E&O | Fireman's Fund | $1M employee / $2M aggregate |
| Automobile liability | Arch | $1M combined single limit |
| Garagekeepers | Arch | $100K comprehensive and collision at each of four sites |
| Umbrella | Fireman's Fund | $5M occurrence / aggregate |
| Excess liability | Chubb / Federal | $5M excess of scheduled Union $5M |
| Employment practices | Chubb / Federal | $1M aggregate; generally $25K retention |
| Crime | Chubb / Federal | $500K principal coverages; social engineering sublimits |
| Crime | Fireman's Fund | Generally $25K; smaller outside-premises limit |
These are contractual limits, not necessarily additive amounts. Coverage, attachment, aggregates, exclusions and policy periods must be verified before presenting a combined total.
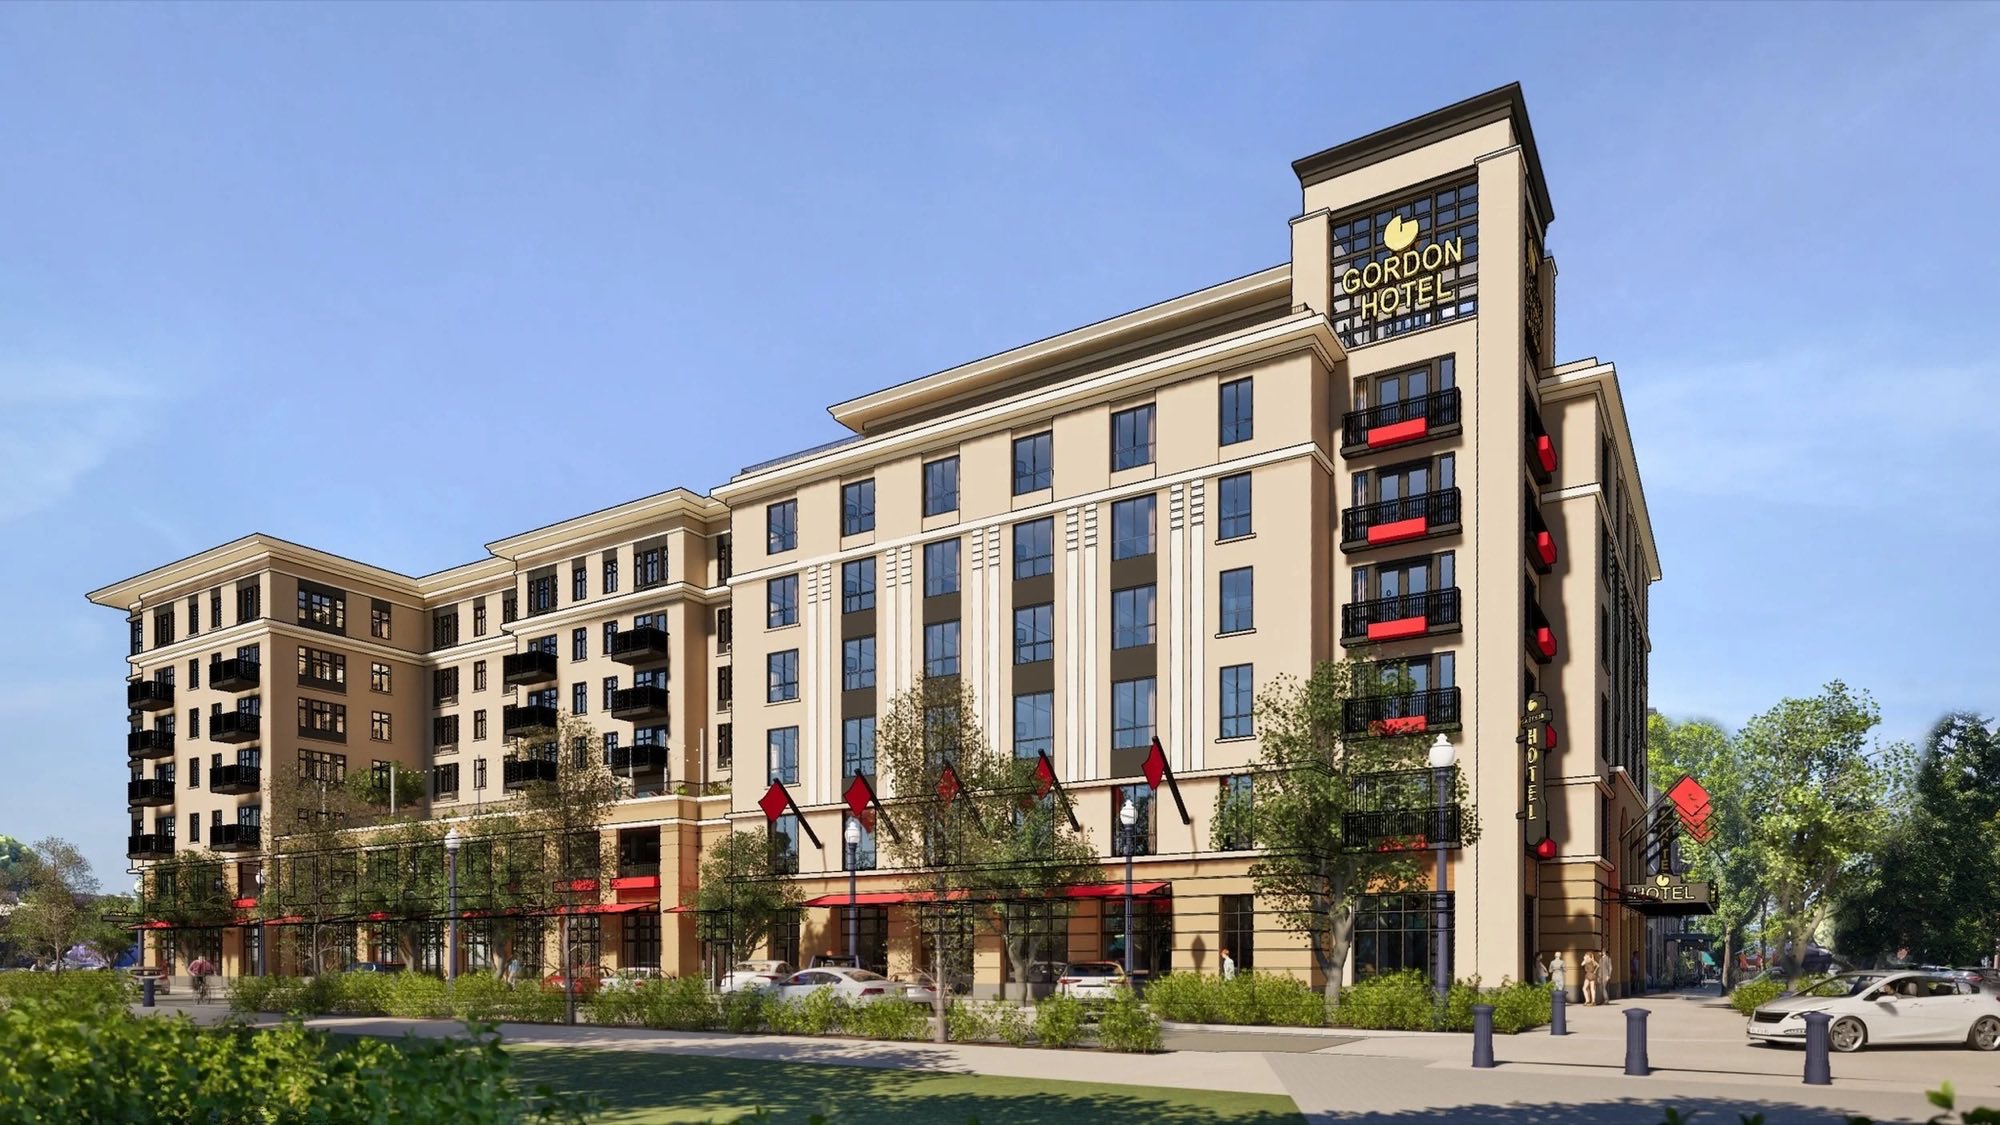
Chubb specifically excludes "The Gordon Lofts" in form 07-02-2222, PDF page 45. The March package identifies Gordon Lofts among the insured properties. This documents an exclusion in Chubb's excess layer, not proof that every other excess policy excludes it.
The Chubb excess form excludes construction, development, maintenance and renovation. The Fireman's Fund primary GL and umbrella contain construction restrictions but distinguish regular maintenance and tenant improvements. These differences need evaluation against Obie's actual work and any subcontracting. Sources: Chubb PDF pp.47 to 48; Fireman's Fund package p.206; umbrella p.61.
Both Fireman's Fund primary GL and umbrella contain cross-suits exclusions applying to claims between insureds. With numerous scheduled legal entities, intercompany agreements and leases are important to evaluate. Sources: package p.205; umbrella p.47.
The property declarations show a $5 million event/annual aggregate for earth movement at locations 2, 26, 27 and 29, subject to a 10% property deductible, minimum $100,000, and a 336-hour time-element deductible. The insured values and recovery assumptions should be tested against these limitations. Source: package PDF p.30, Property-Gard declarations PR 4 of 8.
The primary GL declarations show $100,000 for damage to premises rented to the insured, while the umbrella's primary schedule lists $1 million. This creates a potential attachment discrepancy requiring a carrier response, rather than an automatic conclusion that the difference is uninsured.
The insurance breakdown workbook also identifies a Travelers $10 million excess layer, cyber, separate EPL, flood, earthquake and Elmers property placements. The associated issued policies were not supplied. Workers compensation and employers liability also remain unverified from the supplied materials.
I would prioritize obtaining the issued underlying-change endorsement for Chubb, the Travelers excess policy, and the complete location and entity schedule. Then review actual construction activities, the group's intercompany relationships, earthquake loss exposure, and valet vehicle concentrations.
Review limitationAll nine PDFs, totaling 667 pages, were indexed, and the relevant declarations, schedules and key operative clauses were reviewed. This is a provisional, evidence-based broker meeting review, not a completed clause-by-clause policy audit or coverage determination.
Reading the market
The insurance market moves in cycles, and conditions vary by line and by account. Property may be soft right now while general liability runs firm. Until the carriers come back with real terms, the honest read is in the middle.
A mixed market. Some lines firm while others ease, and carrier appetite shifts by class and by account. Outcomes depend on the specific line and how the risk is presented. This is where Obie's lines sit today.
Carriers tighten. Rates rise, capacity contracts, underwriting gets stricter, and terms narrow. Accounts compete on how well they present their risk.A mixed market. Some lines firm while others ease, and carrier appetite shifts by class and by account. Outcomes depend on the specific line and how the risk is presented. This is where Obie's lines sit today.Carriers compete for business. Rates ease, capacity is ample, terms broaden, and buyers have more options and leverage.Property, catastrophe and habitational liability each move on their own cycle, so a program is only as strong as how its specific exposures are presented.
Hotels and multifamily get a closer underwriting look on abuse, liquor and guest exposures. The program that explains its controls competes better.
The difference between accounts is how well the risk is documented and told. That is the work we do before the first submission.
The work does not stop
So a turn in the cycle never catches Obie off guard.
Against the actual loss trend, not a one-time assumption.
Competition is not a one-time event. It is how every renewal stays sharp.
What the documents show
Drawn directly from the policies Obie shared with us. Each one is a conversation, not a conclusion.
Your excess layers renew in January and the program beneath them renews in March. We would confirm every layer recognizes the March 2026 umbrella and then bring all of it onto one date.
For four hotels and a residential building, this protection is a single $1M limit that also pays defense, with nothing above it.
The apartment building sits outside the excess layers, at roughly a quarter of the liability limits the rest of the portfolio carries.
Every liability layer excludes construction, and the first excess extends that to maintenance and renovation. We would map where that work is and is not covered.
The four hotels share one $5M limit. We would set it next to each hotel's replacement value so ownership can choose what to carry.
Every lever on the table
We would model Obie's program at more than one retention level so ownership sees the trade-offs, not a single quote. The figures come from the live proposal once we are in the market.
Structure A
The carrier holds more of the risk. Higher premium, most predictable cost.
Structure B
A measured amount of retained risk in exchange for meaningful premium savings.
Structure C
Lowest premium, more variability. Strongest when losses stay low.
FiguresSpecific premiums, limits and retentions are reviewed live from the proposal.
Where we would start
The first ninety days, in order.
Every current policy read against lender requirements and the entity schedule.
Written confirmation that each excess layer recognizes the current underlying program.
Abuse and molestation, liquor and garagekeepers priced as options, not assumed.
A statement of values by building, set against the earthquake limit and deductible.
In writing
What we commit to from the day we are appointed.
The market plan is agreed with ownership before a single submission goes out.
OwnerLogan Haugen and Corey Dixon
Entities, locations and values maintained as one document and updated with every change.
OwnerLogan Haugen and Corey Dixon
Each item from the program review written down, owned and carried until it is resolved.
OwnerLogan Haugen and Corey Dixon
Strategy meeting at least 120 days before each renewal date.
OwnerLogan Haugen and Corey Dixon
Your HUB Team
Each person owns a piece of the account and answers for it directly.
Lead producer
Senior Vice President, Commercial Lines Producer
Lead producer
Team Haugen Lead
Senior Vice President, Commercial Lines Producer
Logan and Corey are the leads on this account, both accountable for the end-to-end Obie program and the carrier relationships.
Associate Advisor, Commercial Lines
Associate Advisor, Commercial Lines
We look forward to presenting it to you during our next meeting.
Thank you for taking the time to discuss. The team behind this review is here to answer any of your questions. We look forward to the next steps.